
Africa’s agricultural tractor market is projected to grow from roughly $1.8 billion in 2026 to as much as $3.54 billion by 2035, an annual growth rate of nearly 8 percent, according to industry market analysis. A separate assessment puts the current tractor and machinery market at $2.58 billion in 2026, rising to $3.26 billion by 2031
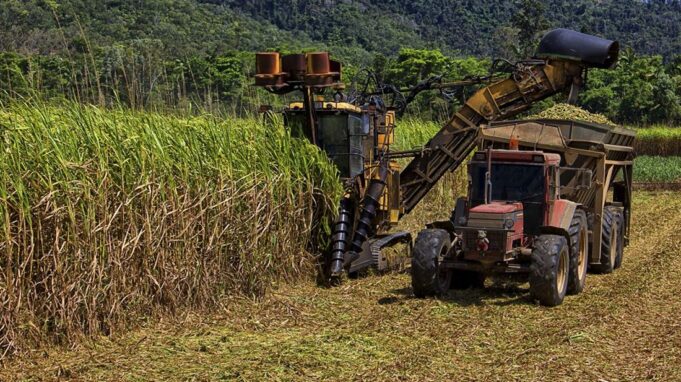
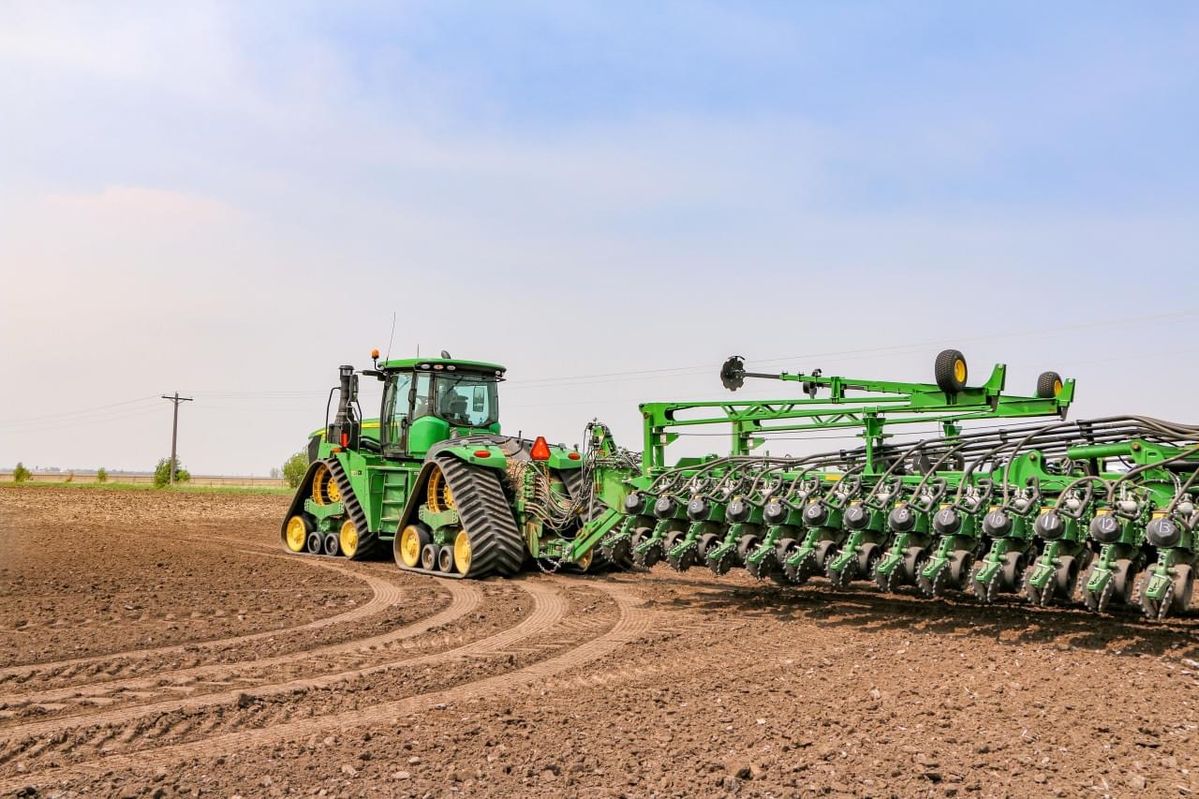
Africa’s agricultural tractor market is projected to grow from roughly $1.8 billion in 2026 to as much as $3.54 billion by 2035, an annual growth rate of nearly 8 percent, according to industry market analysis. A separate assessment puts the current tractor and machinery market at $2.58 billion in 2026, rising to $3.26 billion by 2031 — different methodologies, but the same underlying story: after decades of Africa lagging far behind other regions in mechanization, tractor demand across the continent is accelerating sharply.
The growth is being driven by a familiar combination of factors reshaping African agriculture more broadly: government subsidy and hire-purchase schemes lowering the capital barrier for farmers, the spread of pay-per-use digital tractor-hire platforms that let smallholders access machinery without owning it outright, and the establishment of local, completely-knocked-down assembly lines that reduce import costs and currency exposure for manufacturers and buyers alike.
Where the growth is concentrated
Nigeria anchors much of the continent’s tractor demand, propelled by federally subsidised loan programmes and a northern grain belt where ageing two-wheel tractor fleets are due for replacement under state-level equipment subsidy schemes. Kenya, meanwhile, is recording the fastest rate of expansion in the market, as horticulture exporters increasingly standardise around precision implements to meet the quality and consistency demands of international buyers.
County-level cooperatives in Kenya and Tanzania are also playing an outsized role, lowering effective rental costs for smallholders by pooling machinery access across multiple farms — a model that echoes the mechanization-as-a-service approach gaining traction in policy circles across the continent. Medium-scale commercial farms are separately scaling up their own equipment fleets to support double-cropping, adding another layer of demand growth distinct from the smallholder hire-platform segment.
The early signs of electrification
Perhaps the most forward-looking element of the market’s trajectory is the emergence of diesel-to-electric conversion programmes, gaining early but genuine traction as part of national agricultural modernisation policies in East Africa. While still a small fraction of the overall market, the shift reflects two converging pressures: the volatility and cost of imported diesel fuel for farmers already operating on thin margins, and tightening emissions standards in countries like Ghana and Ethiopia, which are pressuring equipment suppliers to certify cleaner powertrain configurations to remain compliant with new national thresholds.
Electric tractors and equipment face obvious infrastructure hurdles in markets where reliable grid electricity is itself inconsistent — but the same solar-power innovations already reshaping irrigation across smallholder farms offer at least a partial answer, with solar charging infrastructure emerging as a parallel investment theme alongside electrified farm equipment pilots.
Currency risk remains the market’s biggest headwind
Because the vast majority of tractors and major implements sold in Africa are still imported, currency volatility remains one of the sector’s most persistent structural risks, with import-dependent supply chains exposed to margin erosion whenever local currencies weaken against the dollar or euro. It’s a major reason why local assembly — completely-knocked-down kits assembled domestically rather than shipped as finished units — has become a strategic priority for manufacturers looking to compete on price while insulating themselves from the worst of that currency exposure.
What it means for the next decade
Whichever market estimate proves closer to reality, the direction is unambiguous: Africa’s tractor and machinery market is entering a genuine growth phase after years of underinvestment relative to farm labour demand. The mix of subsidised hire schemes, digital leasing platforms, local assembly and early-stage electrification suggests the next decade of African mechanization will look meaningfully different from the last — less defined by isolated government tractor giveaways, and increasingly shaped by commercially sustainable equipment-access models built to match how African farmers actually work their land.